VA House Hacking in Connecticut: Buy a 2 to 4 Family with Your VA Loan
Updated October 2026
Reviewed by Thomas Sloan, Certified Mortgage Advisor, GoRascal (company NMLS 2072896, individual NMLS 1629628)
Veterans and eligible service members can use a VA loan to buy a 2, 3, or 4 unit property with no down payment, as long as they live in one of the units as their primary residence. The rent from the other units can help cover the mortgage. Chris Mentley, a Connecticut real estate agent with New Haus Group (license RES.0824776), helps veterans find and underwrite 2 to 4 family properties across Central Connecticut and the Hartford area, including New Britain, Meriden, Middletown, Hartford, and East Hartford.
Can you buy a multifamily with a VA loan?
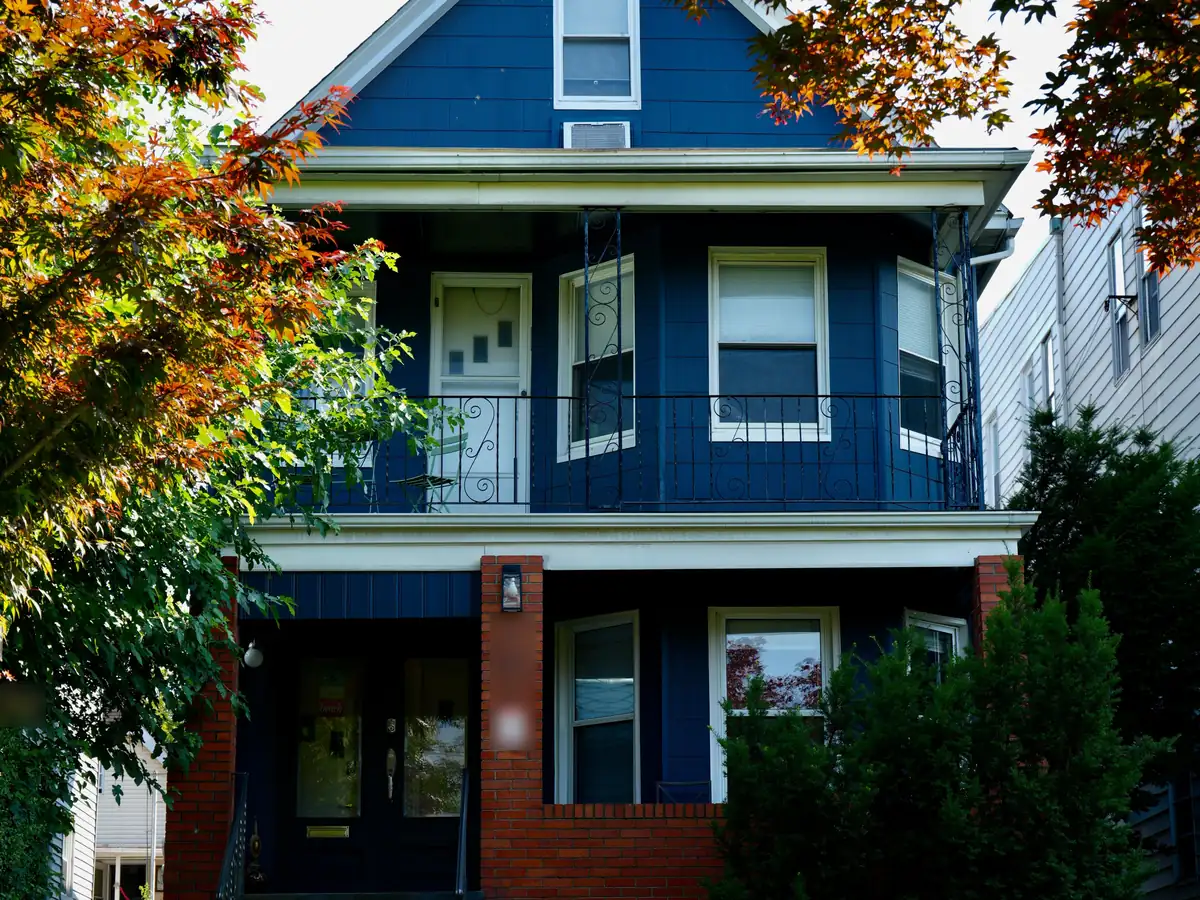
Yes. The VA program covers properties with up to 4 units, as long as you live in one of them as your primary residence. That's a duplex, triplex, or fourplex. For one veteran, five units or more is commercial lending, not VA. Two eligible veterans buying together can go up to 6 units plus 1 commercial space, if one of them runs the business.
You live in one unit, rent the others, and the tenants help pay the mortgage. Investors call it house hacking. For a veteran, it's the lowest-cost way I know to buy a first rental property.
What are the occupancy rules?
You have to intend to live in one unit as your primary residence. Lenders generally expect you to move in within about 60 days of closing. If you're on active duty, your spouse living there can satisfy occupancy.
There's no VA rule that says you have to stay 12 months. Some lenders use it as a rule of thumb, but occupancy is about your intent when you buy: you can't buy planning to move out and rent the whole building. If life changes later and you move, you can keep the VA loan and rent your unit too.
Do you need a down payment?
Not if you have full entitlement. Since 2020, veterans with full entitlement have no VA loan limit and can buy with zero down, as long as the lender approves the loan. You usually have full entitlement if you've never used your VA benefit, or if you've paid off and sold the home from a previous VA loan.
If you're still using part of your entitlement on another VA loan, the county loan limit applies and you may need some money down. Your Certificate of Eligibility shows where you stand.
Can rent from the other units help you qualify?
Yes, but the VA has two conditions. Under the VA Lender's Handbook, the lender can count prospective rent from the other units only if:
- You have at least 6 months of mortgage payments in the bank (principal, interest, taxes, and insurance). Home equity doesn't count.
- You're likely to succeed as a landlord. That usually means prior landlord or property management experience, or a property management company hired to run the other units. What counts is flexible: a property management contract, property management training, or a letter from an owner confirming you managed their property for 2 years have all worked.
On a multifamily purchase, 75% of the market rent counts toward your income, leaving room for vacancy and repairs. Example: if the other unit of a 2-family rents for $1,800 a month, a lender using 75% would count $1,350 toward your qualifying income. If you can qualify on your own income without the rent, the reserve and experience rules generally don't come into play.
Not every lender knows these rules well, and some add their own requirements. A lender who does VA multi-units regularly makes a real difference.
Keeping your current home as a rental? If you move out of a home you own and keep it, 100% of its market rent can offset that home's mortgage payment, with no lease required.
What does the VA funding fee cost?
It's a one-time fee that can be rolled into the loan:
| Down payment | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% or more | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
On a $400,000 loan with zero down and first use, that's $8,600. If you have a VA disability rating of 10% or higher and receive compensation for it, you're exempt and pay $0.
What do VA appraisals check on a multifamily?
Every unit has to meet the VA's Minimum Property Requirements: safe, structurally sound, and sanitary. Peeling paint only matters on homes built before 1978, which covers most Central CT 2 to 4 families, and it doesn't apply to detached structures like garages. Items like a missing handrail can sometimes be waived when the lender knows the guidelines. I flag the likely issues before you make an offer, not after the appraisal.
Where are the 2 to 4 families in Central Connecticut?
Most of the 2 to 4 family stock in my market is in the older city neighborhoods of New Britain, Meriden, Middletown, Hartford, and East Hartford. Those towns are where house hacking numbers tend to work best. See the investor page for how I underwrite each deal.
Not looking for a multifamily?
A single family home works great with a VA loan too. You get the same zero down with full entitlement and the same funding fee rules, without the rental income or landlord requirements. If you need to move fast, it's the simpler path. See the full guide to VA loans in Connecticut.
I help veterans buy single family homes, condos, and 2 to 4 families across Central Connecticut. One note on condos: the building doesn't need VA approval before you offer, but the VA won't approve a condo that bans or heavily restricts renting units out, so I check the condo rules first.
How does Chris help veterans buy a home?
I've been a landlord myself, and I underwrite every property before you see it: rents, taxes, operating costs, and the big-ticket systems that sink a deal. I'll also help you line up a lender that's comfortable with VA multi-unit loans. I'm a Military Relocation Professional (MRP), certified by the National Association of REALTORS®.
Call or text 860-919-7377, email [email protected], or use the form below.
Run the numbers on your next home
Tell me the towns you're looking at and where you are with your VA benefit. It goes straight to me. Prefer to talk? Call or text (860) 919-7377.
Frequently asked questions
Can I buy a multifamily with a VA loan in Connecticut?
Yes. A VA loan can be used on a property with up to 4 units, as long as you live in one unit as your primary residence. The other units can be rented.
Do I need a down payment to buy a 2 to 4 family with a VA loan?
Not with full entitlement. Veterans with full entitlement have no VA loan limit and can buy with zero down if the lender approves the loan.
Can rental income from the other units count toward qualifying?
Yes, if you have at least 6 months of mortgage payments in reserves and a reasonable likelihood of success as a landlord, usually shown by landlord experience or a property management company. On a purchase, 75% of the market rent counts toward income.
How long do I have to live in a VA-financed multifamily?
Lenders generally expect you to move in within about 60 days of closing. There's no VA 12-month rule; occupancy is about your intent when you buy. If your plans change later, you can move out and rent your unit.
What is the VA funding fee on a purchase?
2.15% of the loan amount on first use with less than 5% down, and 3.3% after first use. It drops to 1.5% with 5% down and 1.25% with 10% down. Veterans with a VA disability rating of 10% or higher who receive compensation are exempt.
Can I use a VA loan to buy a single family home?
Yes. Single family homes are the most common VA purchase. Zero down with full entitlement, the same funding fee rules, and no rental income or landlord requirements. Condos are approved during the purchase, and approval is usually routine unless the condo bans or heavily restricts renting units out.
Can I use a VA loan on a 5 unit building?
Not as a single veteran. The VA program covers up to 4 units for one veteran. Two eligible veterans buying together can go up to 6 units plus 1 commercial space.
Which Central CT towns have the most 2 to 4 family properties?
New Britain, Meriden, Middletown, Hartford, and East Hartford have the largest share of 2 to 4 family inventory in Chris Mentley's market area.
How do I contact Chris Mentley about a VA multifamily purchase?
Call or text 860-919-7377, or email [email protected].
Sources
- VA funding fee and closing costs, VA.gov
- VA home loan entitlement and limits, VA.gov
- VA Lender's Handbook (VA Pamphlet 26-7), Chapter 4: rental income on multi-unit properties
- VA loans overview, Mass.gov real estate education
This page is general information, not a loan approval or financial advice. Lender requirements vary; confirm eligibility and terms with a VA-approved lender.